
Key takeaways
- Checked and verified against current regulatory guidelines by practising CAs/CSs.
- Covers key requirements, step-by-step registration procedures, and statutory compliance timelines.
- Includes actionable insights tailored for Indian founders and business owners.
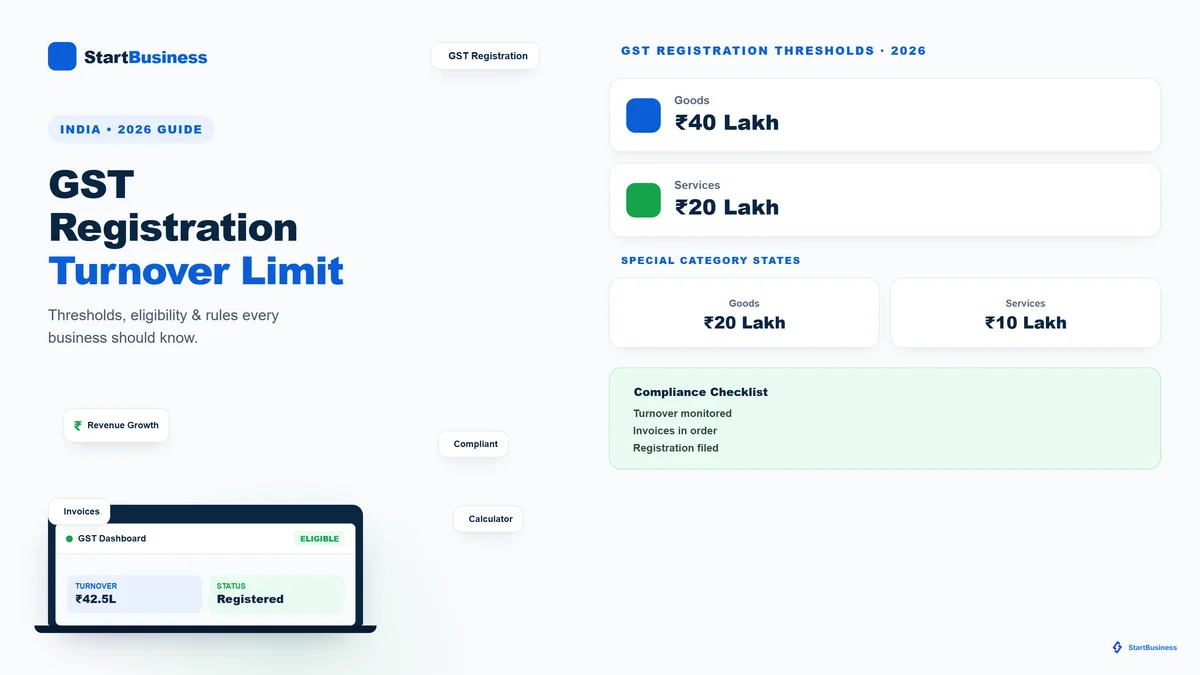
| Quick Answer The GST registration turnover limit in India is the annual aggregate turnover above which GST registration becomes mandatory. |
|---|
The GST registration threshold in India generally depends on aggregate turnover, the type of supply and the state or Union Territory. The usual threshold is ₹40 lakh for eligible businesses exclusively supplying goods and ₹20 lakh for services or mixed supplies. Lower thresholds apply in certain states and situations, and compulsory-registration rules or specific exemptions may change the result.
Every business owner in India faces the same question early on: do I need to register for GST, or not? The answer depends on two things — how much you earn and what you sell. Cross the limit and registration is compulsory. Stay below it and you can usually operate without GST, unless a special rule applies.
This guide explains the GST registration turnover limit in India, how aggregate turnover is calculated, and exactly who must register in 2026. It is written for freelancers, shop owners, e-commerce sellers, and founders who want a clear answer without the jargon. If you decide you need to register, our GST registration service can handle the process for you.
What Is the GST Registration Turnover Limit?
The GST registration turnover limit is the minimum aggregate turnover a business can earn in a financial year before GST registration becomes mandatory. Below this limit, registration is generally optional. Above it, registration is required by law.
Two factors decide which limit applies to you:
• What you supply — goods carry a higher limit (₹40 lakh) than services (₹20 lakh) in most states.
• Where you operate — four special category states use lower thresholds.
GST Turnover Limit in India (2026): Goods vs Services
The table below shows the complete GST threshold limit for 2026:
| Business type | Most states | Special category states* |
|---|---|---|
| Supply of goods only | ₹40 lakh | ₹20 lakh |
| Services only | ₹20 lakh | ₹10 lakh |
| Goods + services (mixed) | ₹20 lakh | ₹10 lakh |
These are general thresholds, not a substitute for checking the applicable notification. The ₹40 lakh threshold is available only to eligible suppliers exclusively supplying goods, subject to specified conditions and exclusions.
Exceptions to the ₹40 lakh goods limit
The ₹40 lakh limit for goods does not apply if you:
• Supply notified goods such as ice cream, pan masala, or tobacco
• Make inter-state supplies of goods (from one state to another)
• Sell through e-commerce operators
In these cases, the ₹20 lakh limit or compulsory registration applies instead.
Aggregate Turnover Under GST Explained
| Quick Answer Aggregate turnover is the total value of all supplies made under one PAN across India in a financial year. It is calculated PAN-wide, not separately for each state or branch. |
|---|
Aggregate turnover includes:
• Taxable supplies
• Exempt supplies
• Exports of goods and services
• Inter-state supplies under the same PAN
It excludes:
• CGST, SGST, UTGST, IGST, and compensation cess
• Inward supplies taxed under reverse charge
Example
A digital consultant in Delhi earns ₹15 lakh in taxable fees and ₹3 lakh in exempt income under the same PAN. Her aggregate turnover is ₹18 lakh — below the ₹20 lakh services limit, so GST registration is not yet mandatory. Her aggregate turnover is ₹18 lakh, below the general ₹20 lakh service threshold. She should also check whether any compulsory-registration provision applies. An inter-state service supply or a supply to an overseas customer does not, by itself, always require registration below the threshold; the applicable exemption, place-of-supply and export conditions must be examined.
When GST Registration Becomes Mandatory
GST registration is mandatory in two situations: when you cross the turnover limit, or when you fall into a compulsory category — even with zero turnover.
Cases Where GST Registration May Be Required Below the Turnover Threshold
Certain categories of businesses may need GST registration even when their aggregate turnover is below the usual threshold. The applicable law also contains exemptions and exceptions, so check the specific facts before concluding that registration is compulsory.
Situations requiring particular attention include:
- Inter-state taxable supplies of goods, subject to applicable exemptions.
- Casual taxable persons and non-resident taxable persons making taxable supplies, subject to the relevant rules.
- Persons required to pay GST under reverse charge in cases covered by the law.
- Agents making taxable supplies on behalf of other taxable persons.
- Input Service Distributors.
- Persons required to deduct GST TDS and electronic commerce operators where the law requires registration.
- Certain suppliers making taxable supplies through e-commerce operators, subject to the applicable provisions and exemptions.
- Specified online service providers supplying customers in India.
The registration requirement depends on the type of supply, the applicable notification and the person's circumstances. If you are unsure, check the relevant GST provisions before starting taxable supplies.
GST for Startups and Online Businesses
Startups
There is no separate GST exemption for startups — they follow the same thresholds as every other business. A startup earning below ₹20 lakh in services is not forced to register on turnover alone. In practice, most funded startups register early because they sell across states or need input tax credit. Choosing the right structure first — a Private Limited Company or an LLP — keeps your GST and compliance clean from day one.
E-commerce and online sellers
This is where the turnover limit stops applying. If you sell goods through an e-commerce operator like Amazon or Flipkart, GST registration is mandatory from your first sale — turnover does not matter. Service providers selling online may still use the ₹20 lakh limit unless another rule applies.
Solo founders should also note that a One Person Company has its own ₹2 crore turnover ceiling, separate from GST — worth planning for as you grow.
Real-World Turnover Scenarios
| Business | Turnover | GST required? |
|---|---|---|
| Freelance designer, Delhi, local clients | ₹18 lakh | No — below ₹20 lakh services limit |
| Same freelancer, with an overseas client | ₹18 lakh | Yes — export / inter-state rules |
| Clothing shop, Maharashtra (goods) | ₹35 lakh | No — below ₹40 lakh goods limit |
| Same shop after growth | ₹42 lakh | Yes — crossed ₹40 lakh |
| Amazon seller (goods) | ₹5 lakh | Yes — mandatory, any turnover |
| Consultant in Nagaland (special state) | ₹11 lakh | Yes — above ₹10 lakh limit |
| Local tuition service, Karnataka | ₹12 lakh | No — below ₹20 lakh, single state |
Key point: turnover is only half the test. The nature of your supply — inter-state, online, or occasional — can override the limit entirely.
Voluntary GST Registration
You can register for GST even when your turnover is below the limit, and many small businesses choose to. The main benefits are:
• Input tax credit — claim back the GST paid on your purchases and expenses.
• Credibility — many B2B clients and larger buyers prefer or require a GSTIN.
• Nationwide reach — sell across states and on e-commerce platforms without restriction.
• Growth-ready — no last-minute scramble the day you cross the threshold.
The trade-off is compliance: once registered, you must file returns on time for every period, even in months with no sales. Ongoing ROC and annual compliance support keeps this manageable.
Common Mistakes Businesses Make
• Counting only taxable sales and ignoring exempt supplies and exports when checking the limit
• Calculating turnover state-by-state instead of PAN-wide across India
• Assuming e-commerce sellers get the ₹40 lakh cushion — most must register from the first sale
• Applying the ₹40 lakh goods limit to services (services follow ₹20 lakh)
• Listing many states under the ₹10 lakh limit — it applies only to four
• Waiting until turnover crosses the line before tracking it — start monitoring well before
Conclusion
The GST registration turnover limit is simple once you separate the two tests: your aggregate turnover (₹40 lakh for goods, ₹20 lakh for services in most states) and your category (e-commerce, inter-state, and casual supply require registration regardless). Track both and you stay ahead of penalties.
If you are unsure where you stand, our team can confirm your position and register you correctly the first time. Explore StartBusiness services — from GST registration to trademark registration — and speak to an expert before your next financial year begins.
Frequently Asked Questions
What is the GST registration turnover limit in India?
It is the annual aggregate turnover above which GST registration becomes mandatory. In 2026, it is ₹40 lakh for goods and ₹20 lakh for services in most states, and ₹20 lakh / ₹10 lakh in the special category states of Manipur, Mizoram, Nagaland, and Tripura.
What happens if I cross the GST limit without registration?
You can face tax dues on the sales you made after becoming liable, plus interest and a penalty of 10% of the tax due or ₹10,000, whichever is higher. Deliberate evasion can attract a penalty of up to 100% of the tax due.
Is GST mandatory from the first sale?
Only in certain cases. If you sell goods inter-state, sell through e-commerce operators, or fall under reverse charge, GST is mandatory from the first sale. Otherwise, it applies only after you cross the turnover limit.
Can I avoid GST if my turnover is below the limit?
Yes, if you stay below the threshold and do not fall into any compulsory category. But inter-state suppliers and e-commerce sellers cannot avoid it, regardless of turnover.
At what turnover is GST registration required?
Registration is required once aggregate turnover crosses ₹40 lakh for goods or ₹20 lakh for services in most states (₹20 lakh and ₹10 lakh in special category states). Apply within 30 days of becoming liable.
Is the GST registration limit 20 lakhs or 40 lakhs?
Both apply. ₹40 lakh is for businesses supplying only goods in most states. ₹20 lakh is for service providers and mixed suppliers. Special category states use lower limits of ₹20 lakh and ₹10 lakh.
What is aggregate turnover under GST?
Aggregate turnover is the total value of all supplies — taxable, exempt, exports, and inter-state — made under one PAN across India in a financial year. It excludes GST itself and reverse-charge inward supplies.
Who is eligible for GST registration in India?
Anyone crossing the turnover threshold must register. Anyone below it may register voluntarily. Certain categories — inter-state suppliers, e-commerce sellers, casual and non-resident taxable persons — must register regardless of turnover.
We handle business incorporation and deed drafting end-to-end, tailored to your needs.
Practising from Deccan Gymkhana, Pune since 2017. Has handled 1,000+ incorporations and ongoing compliance for founders across Maharashtra, from single-partner proprietorships to funded private limited companies.